


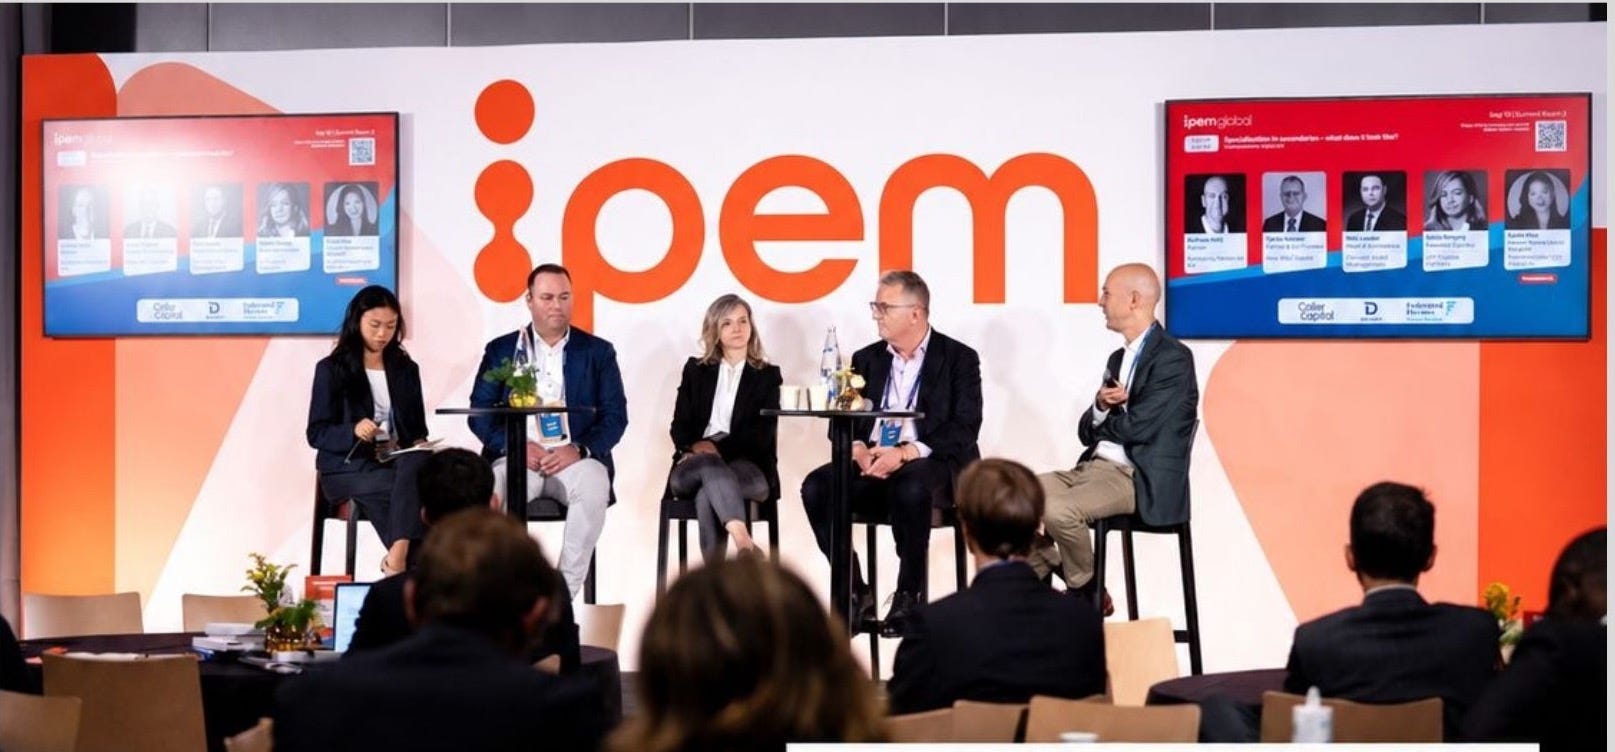
Gone are the days when everything was done under the same fund: infrastructure, buyout, venture capital, all bundled into one vehicle. That was the private equity universe of the 1980s, and unwinding it has taken the industry the better part of four decades. At IPEM Global's Secondaries Summit, a panel of four buyers: Nick Lawler of Churchill Asset Management, Stela Rakipaj of LGT Capital Partners, Tjarko Hektor of New 2nd Capital, and Andres Hefti of Multiplicity Partners, made the case that secondaries is now living through its own version of that same unbundling, splitting further into distinct, specialized strategies rather than converging into a single, one-size-fits-all trade.
The opening session made the case for the secondaries market’s size. This one made the case for why size, on its own, no longer tells you very much. Rather than a lineup of buyers arguing over the same territory, the panel represented a market that has genuinely split into distinct bands, some players built for scale, others built to stay small enough that the biggest generalists never bother competing with them.
A market that has split into bands, not tiers
Across the conversation, ticket sizes discussed ranged from as small as $3–5 million on the LP-led side up to $300 million or more for larger middle-market transactions, with GP-led activity clustering in the $10–100 million range and one strategy built specifically around $30–40 million North American deals. What emerged wasn’t a single market with a few large players at the top, it was several adjacent markets, each defined by a ticket-size band narrow enough that a buyer built for one band rarely has a natural reason to compete in another.
One recurring theme was deliberate positioning below the radar of the largest generalist funds: a segment of the market was explicitly described as tickets that “don’t move the needle” for the biggest players, which several panelists treated as a structural advantage rather than a limitation, being too small to attract mega-fund competition keeps pricing more rational. At the other end, a dedicated niche strategy was described as going wherever asset type, geography, or structure put a deal outside what the other approaches on the panel were built to do.
FOUR SHAPES OF “SPECIALIZATION,” NOT NAMED TO A FIRM
Across the discussion, four distinct specialization models emerged: platform depth built on a large base of existing portfolio companies and proprietary financial visibility; middle-market focus deliberately sized below the interest of large generalists; a dedicated GP-led strategy built around sustained, education-led relationship investment with sponsors; and a niche mandate built to go after deals the other three approaches structurally can’t reach. None of the four panelists claimed the other models were invalid, the implicit consensus was that the market currently has room for all of them.
A market with room, and a market with pressure
The panel’s read on the broader environment was double-edged. Zooming out, one framing stuck: the private equity universe of the 1980s ran everything, infrastructure, venture, buyout, out of the same fund, and specialization has been a decades-long unbundling process ever since. Secondaries, on that view, still has a long runway left to specialize further, and competition along the way was described as healthy rather than threatening.
The near-term dynamics were more mixed. Large generalist players are putting real pressure on pricing at the top of the market, which the panel framed as good news for buyers generally: there’s room for more complex, harder-to-execute transactions further down the ticket-size spectrum, but less good news for sellers on both the GP-led and LP-led sides, who are facing tighter pricing precisely where the generalists compete hardest. One concern raised repeatedly cut across every strategy represented: human capital. Finding and training the specialized underwriting talent this fragmenting market needs was flagged as a genuine constraint on the industry’s ability to keep growing into its own specialization thesis.
“We are as responsible as the GP for making it a success.”
How to differentiate when everyone claims an edge
Asked directly how to stand out, the panel converged on two headline answers: transparency and reputation, backed by a more granular checklist. On transparency, the point was made that a buyer’s obligation to a portfolio company’s success extends well past closing, framed as being equal to the GP’s own obligation, not a passive financial position taken and then left alone. That posture, the panel argued, is what actually wins repeat deal flow and reputational trust in a market where GPs are choosing a long-term capital partner, not just a price.
THE “CAPITAL PARTNER” CHECKLIST
Beyond transparency and reputation, the panel’s differentiation framework came down to five habits: sourcing, knowing precisely what you’re going after before you buy, not after; underwriting conviction, built on genuine relationship depth rather than a single data room; active relationship-building with GPs over time; a deliberate willingness to work on less well-known assets and less well-known GPs, where competition is thinner; and prioritizing quality of investment over sheer velocity of dealmaking.
Where specialization goes next
On the forward-looking question, the panel’s list ran longer than a single trend. First and most fundamental: investors are moving away from treating secondaries as a one-size-fits-all allocation, splitting it instead into genuinely distinct sub-strategies. Second, private credit secondaries were flagged as the next asset class likely to develop its own dedicated specialists, following the same maturation path infrastructure secondaries has already been through. Third, geography: the Middle East and Asia were named as PE ecosystems still building out the secondary-market infrastructure that North America and Western Europe already have. Fourth, AI-native secondary players were raised again as an entrant category the incumbents expect to eventually contend with. Fifth, sector specialization more broadly, buyers building focused expertise in specific industries rather than staying generalist across the private equity universe.
The more provocative open question was whether secondaries themselves are becoming a source of alpha, rather than simply a liquidity or portfolio-management tool. One data point offered in that discussion: an estimate that roughly 2.5% of assets bought by secondaries funds from the 2016 vintage have still not been returned to investors, cited as a reason to think carefully about how “specialized” underwriting needs to get as hold periods stretch.